Would Removing Loss Ring-Fencing Help NZ Property Investors?
6667POSTED:
0
Views

Articles by Matthew Gilligan.

If you're a newer investor with high borrowing and a rental property that runs at a loss, removing loss ring-fencing would make a real difference to your cashflow. If you bought years ago and your rents comfortably cover your costs, it would change very little. In 2026, ACT pledged to remove ring-fencing for future rental losses. In my opinion it's the right call, although I think removal is unlikely to happen.
When residential loss ring-fencing was introduced in 2019, I said publicly that it would hurt ordinary mum and dad investors, not wealthy speculators. Seven years on, my view hasn't changed.
Our tax system taxes income on a net basis. If your business makes a loss, you can usually offset it against your other income. That applies to a café, a farm, a commercial building or a share portfolio held on revenue account.
Residential rental property is the exception. Since the 2019/20 income year, a rental loss has not been able to reduce the tax on your salary, and that was still the case at the time of writing. The loss is set aside and carried forward until your rentals make a profit or a property is sold in a taxable sale.
That treats one asset class differently from every other investment, even though the economics of owning a rental are no different. In my view, the rule was designed to make housing investment less attractive.
For more background, read my earlier articles: Loss ring-fencing questions and Ring-fencing update.
In 2026, ACT pledged to remove ring-fencing for rental losses incurred from the date the policy takes effect. Those losses could then be offset against your other taxable income, as they could before 2019.
If brought into force, this change would cover both existing homes and new builds. Losses already ring-fenced would remain under the current rules, so any losses you've carried forward since 2019 wouldn't be released against your salary.
Ring-fencing does little to established investors. People who bought years ago, carry modest debt and collect rents well above their costs rarely make a loss, so the rule barely touches them.
The people it hurts are newer investors. They're salary earners with one or two properties, high borrowing and a weekly top-up from their own pocket. They're building long-term security for their families, and they carry the cashflow strain.
Take someone on a $100,000 salary with a $10,000 rental loss. Before 2019, they would have been taxed as if they earned $90,000, which at a 33% marginal tax rate is worth about $3,300 a year in cash. Under ring-fencing, that $3,300 waits until some uncertain future year, while the investor still covers the shortfall every week.
The rule favours those who are already established and penalises those trying to get started.
| Taxable income | Tax rate | Tax saved each year on a $10,000 rental loss without ring-fencing | Tax saved each year with ring-fencing |
|---|---|---|---|
| Up to $15,600 | 10.5% | $1,050 | $0 (loss carried forward) |
| $15,601 to $53,500 | 17.5% | $1,750 | $0 (loss carried forward) |
| $53,501 to $78,100 | 30% | $3,000 | $0 (loss carried forward) |
| $78,101 to $180,000 | 33% | $3,300 | $0 (loss carried forward) |
| Over $180,000 | 39% | $3,900 | $0 (loss carried forward) |
Figures assume the whole $10,000 loss falls within one tax bracket. Tax rates and thresholds as at November 2026.
Usually not, but it can happen. Ring-fencing is designed to delay deductions rather than remove them. The losses are real expenses such as interest, rates, insurance and maintenance. They carry forward and are used when your residential rentals make a profit, or when you sell a residential property and the sale is taxable, for example under the bright-line test.
The catch is a sale that isn't taxable. Selling a rental doesn't automatically release its losses. If the sale falls outside the bright-line test and the other land sale rules, the losses stay ring-fenced. You can still use them against income from another residential rental you own, now or in the future, but if you leave residential property investment for good, they may never be used.
Removing ring-fencing would simply recognise genuine costs in the year they're incurred, as happens everywhere else in the tax system. The cost to the Crown is largely one of timing.
New Zealand needs more rental homes, and private investors provide most of them. A rule that makes a rental harder to fund in its early years, when costs are highest, discourages the investment we need. Removing it would improve the cashflow on rental stock, including new builds, and make property investment more attractive.
Yes. How you hold your property will affect whether you benefit if loss ring-fencing is removed. Investors who own directly or through a look-through company are likely to benefit most, because losses can flow through to their personal income.
Rentals held in a trust or an ordinary company need a closer look. Losses in those entities generally stay inside the entity rather than reducing your personal tax, so the change may help less. Your ownership structure should be driven by things like asset protection and estate planning, not by this one rule.
When this article was written (November 2026), coalition negotiations were still underway and nothing was law. Removing loss ring-fencing would give welcome relief to the investors who have carried the weight of the 2019 rules, and would move property back towards being taxed like any other investment.
I'd like to see it happen, but I'm not expecting it. The other parties in any potential coalition will not be on board with this, and I do not think it will be a bottom line for ACT. So my prediction is that it more likely ends up a sacrificial concession during negotiations.
If ring-fencing stays, keep good records of the losses you carry forward. They can be used when your rentals become profitable or a property is sold in a taxable sale. If you're thinking of selling your last rental, check the tax position first, because losses on a non-taxable sale stay ring-fenced.
There's no need to change anything until the outcome is clear. Tax rules can change, so check the current position before you act.
Wondering what removing, or keeping, loss ring-fencing could mean for your portfolio or structure? Request a meeting or call us on +64 9 522 7955. If you're already a client, talk to your Client Services Manager.
Loss ring-fencing stops losses from residential rental property being offset against other income, such as your salary. It has applied since the 2019/20 income year and was still in force in November 2026. The losses are carried forward and used against future residential rental income or a taxable sale.
Not while ring-fencing applies. As at November 2026, rental losses can't reduce the tax on your salary. ACT pledged in 2026 to change this for future losses, but it hadn't become law, so check the current rules before relying on this.
In 2026, ACT pledged to remove ring-fencing for rental losses incurred after the policy takes effect, for both existing homes and new builds. At the time of writing (November 2026), coalition negotiations were still underway, so it wasn't known whether the policy would go ahead.
Under ACT's 2026 proposal, losses already ring-fenced would stay under the current rules. You would still carry them forward and use them against future rental profits or a taxable sale.
It depends on whether the sale is taxable. If it is, for example under the bright-line test, your ring-fenced losses can reduce the taxable gain. If the sale isn't taxable, the losses stay ring-fenced. They can only be used against future residential rental income or a future taxable sale of residential property, so if you don't own another rental, they may never be used.
Yes. As at November 2026, ring-fencing applies to new builds as well as existing homes. ACT's 2026 proposal would remove it for both.
Yes, ring-fencing applies to most owners, including trusts and companies. If the rules were removed, owners holding property directly or through a look-through company are likely to benefit most, because losses can flow through to their personal income.

GRA's services are top notch. I took their property course online over COVID, and then I went to them for a second opinion on some property tax advice I'd received that didn't sound quite right to me. They set me right and saved me from a massive IRD bill. After that I moved over to them full-time. They've given me ongoing sound tax and asset planning advice, and I greatly appreciate and value my annual review meeting with my accountant. I can't speak more highly of GRA in looking out for my best interests.
- Sarah P, June 2023
Investing in residential property?
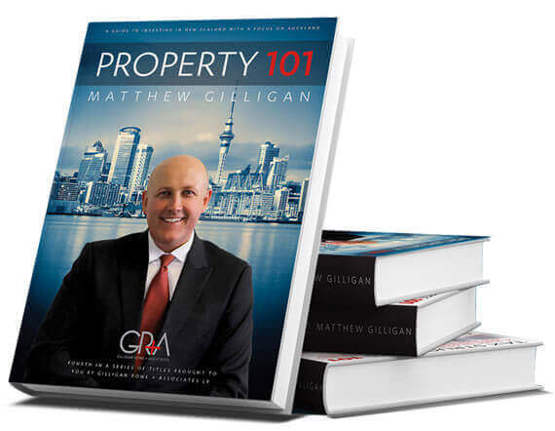
If you're investing in residential property, seeking to maximise your ability to succeed and minimise risk, then this is a 'must read'.
Matthew Gilligan provides a fresh look at residential property investment from an experienced investor’s viewpoint. Written in easy to understand language and including many case studies, Matthew explains the ins and outs of successful property investment.


 Free Resources, Tools & Downloads